
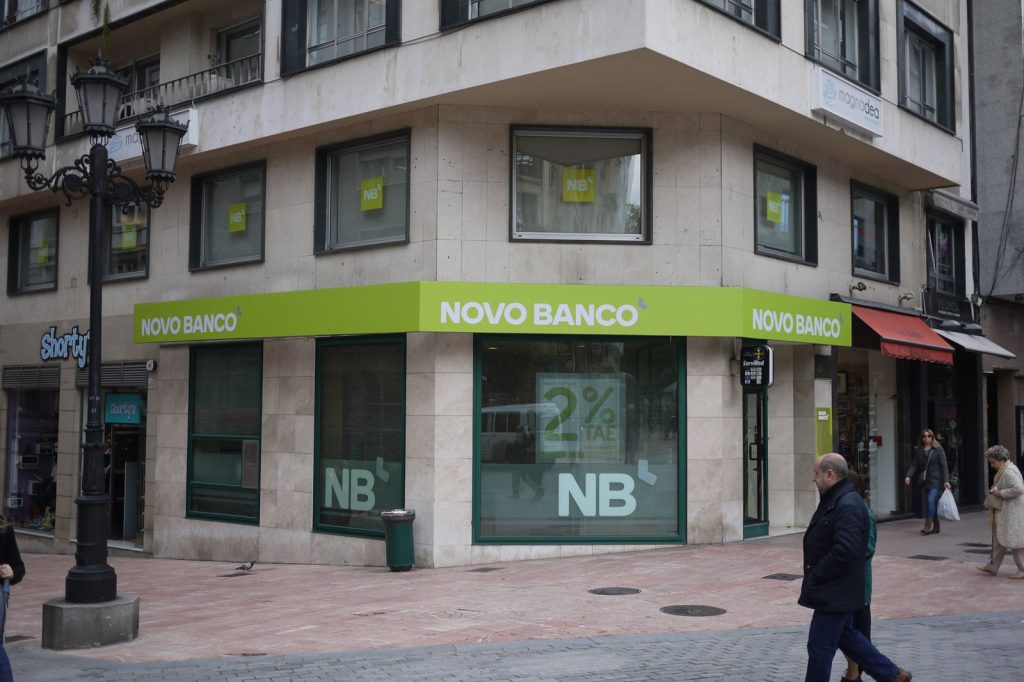
The troubles of Banco Espírito Santo did not start with the central bank’s action on August 3, 2014; they began with the balance sheet. As of March 2011 the bank reported net assets of €80,700 million, served 2.1 million customers and held an average market share of 20.3 % across Portugal.
Those figures made it the second‑largest private financial institution in the country. When an entity of that scale begins to deteriorate, the problems spread quickly. Banco de Portugal recognised the risk and, on that August Sunday, applied a resolution measure rather than allowing an outright collapse.
The authority split the bank into two parts: one retaining the sound operations and the other absorbing the troubled assets. The healthy portion became Novo Banco and received a €4.9 billion recapitalisation from the Portuguese Resolution Fund.
The remaining segment, often described as a “bad bank,” was left with the defaulted loans, worthless securities and other losses linked to the Espírito Santo family’s holdings. Banco Espírito Santo was not a minor player in the national market. It ranked as the ninth‑largest contributor to the PSI‑20 index and had deep connections throughout the Portuguese economy, reaching families, businesses and pension funds.
Its exposure to the Espírito Santo family’s own holding companies proved to be the source of the damage. Within the group, complex and opaque debt structures created a tangled web of risk that eventually choked the bank.
Regulators either failed to detect the building vulnerabilities or acted too slowly to halt the deterioration. The division was intended to create a clean institution. Novo Banco took the deposits, the branch network and the performing loan portfolio, but it also inherited the stigma of being born from a failed predecessor.
Rebuilding public trust will require more than a new name and the €4.9 billion injection. The bad bank, by contrast, functions as a graveyard for toxic assets.
Its purpose is to be wound down over time, selling holdings at a discount to satisfy whatever obligations it can meet. Any shortfall will be absorbed by the Portuguese Resolution Fund. The timing of the collapse added pressure to an already fragile environment. Portugal had only recently exited its international bailout programme, interest rates had fallen and the banking sector was expected to stabilise.
The failure of the second‑largest bank threatened to undermine that progress. Although the central bank’s intervention likely prevented a run on deposits and a wider panic, it also highlighted how precarious the recovery remained.
One large institution, one family’s mismanagement and a web of risky exposures were enough to cause the system to wobble. Looking forward, Novo Banco must demonstrate that it can operate independently. The €4.9 billion cushion provides a buffer, but the bank will need to attract fresh capital and revive lending activity.
Meanwhile, the bad bank will remain a drain on the resolution fund for years as its assets are liquidated. The episode reinforces the lesson that size does not guarantee safety.
Banco Espírito Santo was too big to fail, yet also too big to be rescued intact. The split represented the only viable option—a controlled demolition rather than a happy ending.




