
Market Volatility and the Refining Crunch
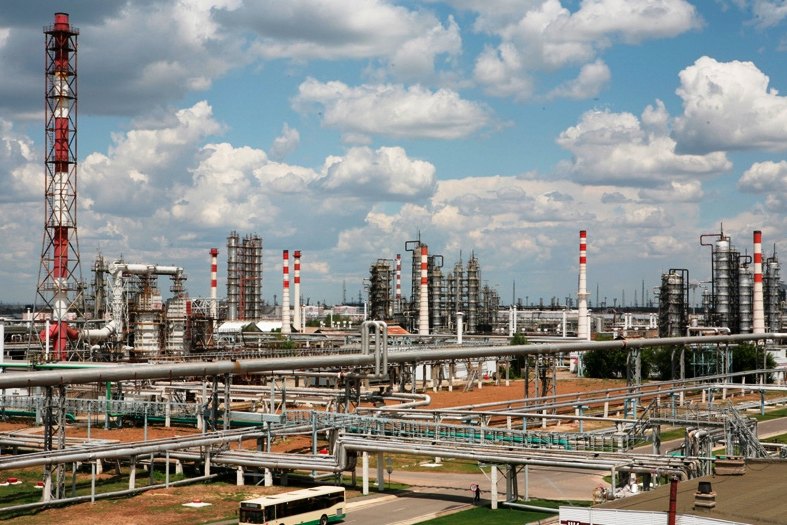
The pattern of disruption has become a recurring variable for global oil traders. Each attack on a refinery or storage depot introduces a new element that must be priced in, and the market has been oscillating in response. The reported strike on an oil depot in Stavropol Krai on April 28, 2024, was part of a broader effort that had already taken significant refining capacity offline. Because these are not production losses—Russia continues to pump crude—the problem lies in processing. Crude oil must either be sold at a discount or stored, while domestic fuel markets tighten.
The consequences have been tangible. By April 2024, Russia was importing gasoline from Belarus, a stark admission of internal pressure for a country that exported roughly 7.2 million barrels per day of crude and petroleum products in 2023, trailing only Saudi Arabia and the United States. The refining losses compromise Russia’s capacity to convert its crude into fuel for its own consumers and for international buyers. This distortion of the normal supply chain has injected uncertainty into pricing. Brent crude fluctuated between $75 and $95 per barrel in the first quarter of 2024, a wide trading band that signals traders are struggling to find a floor. The US Energy Information Administration reported that global petroleum consumption averaged 101.3 million barrels per day in 2023, a figure that underscores how any disruption, even one concentrated in refining rather than production, can reverberate through a system running near capacity.
Complications for OPEC+ and Supply Dynamics
The drone strikes also complicate Russia’s position within OPEC+. As of April 2024, the production agreement required Russia to cut output by 500,000 barrels per day. On closer inspection, the problem is not simply about meeting a quota; it is about the type of production being affected. Drone damage hits refineries, not wells, meaning Russia can still pump crude but struggles to process it. This distorts the usual cause-and-effect of supply cuts, making the market harder to read. In a typical scenario, a production cut reduces the amount of crude available to global markets, directly affecting prices. Here, the refining bottleneck means Russia has crude oil that it cannot efficiently convert, so it must either store it or sell it at a discount on international markets, while domestic shortages force imports. This unusual dynamic undermines the traditional signals that OPEC+ members and traders rely on to gauge supply and demand balances.
Historical Context and Global Significance
Russia’s role in global energy markets is rooted in its long history as a major producer and exporter. The country traces its origins to the medieval state of Kievan Rus’, formed in the 9th century, which later fragmented before the Grand Principality of Moscow unified the region under the Tsardom of Russia in the 16th century. Expansion across Eurasia followed, culminating in the Russian Empire by the early 18th century. The 1917 Revolution overthrew the monarchy, leading to the Soviet Union’s creation in 1922. After decades as a Cold War superpower, the Soviet Union dissolved in 1991, leaving the Russian Federation as its successor state. Today, Russia is a transcontinental country stretching from Eastern Europe to North Asia, the largest by land area, with a long history as a major energy producer and exporter. Since the Soviet era, large-scale industrialization and resource development have made it a key supplier of oil and gas. As a result, disruptions to its refining and export capacity have outsized effects on worldwide fuel availability and pricing, influencing geopolitical and economic stability well beyond its borders. The ongoing drone strikes represent a persistent source of volatility that reshapes how markets assess Russian supply, with implications that extend from domestic fuel shortages in Russia to global price fluctuations that affect consumers and policymakers worldwide.




