
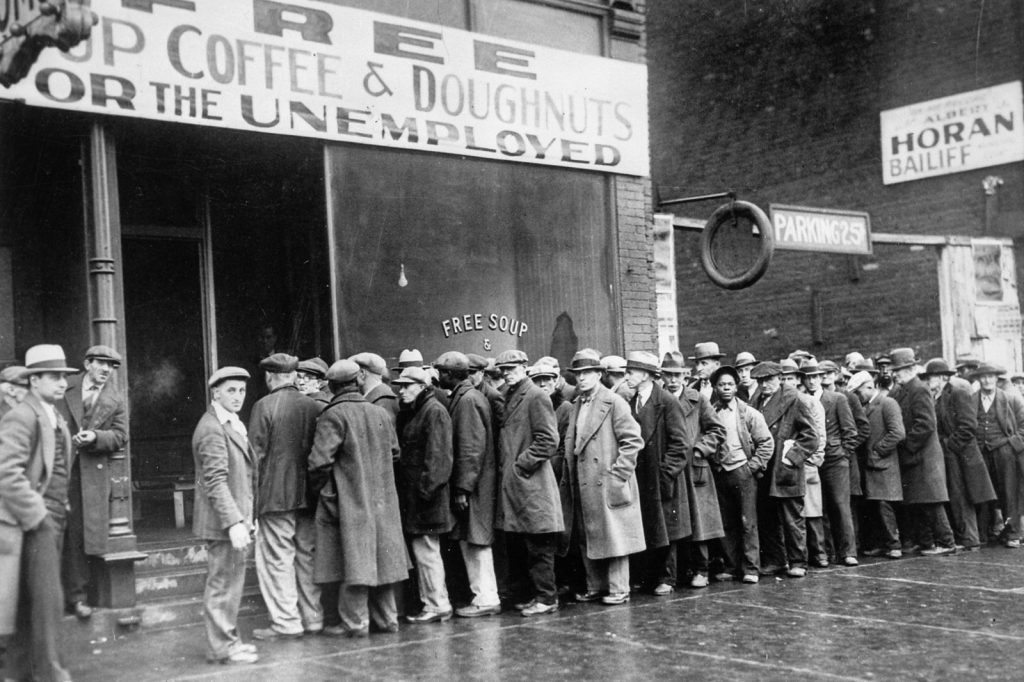
The stock market crash of 1929 did not arrive without warning, yet the mechanism that turned a market decline into a catastrophic collapse remains one of the most studied and feared phenomena in finance. At its heart was the margin call, a process that forced investors who had borrowed heavily to buy stocks into a panicked unwinding that cascaded through the entire financial system. Economists later concluded that this forced-liquidation dynamic was a major factor behind the crash and helped fuel the Great Depression.
The Mechanics of Ruin
Margin accounts allow investors to borrow money from a broker to purchase securities, using those same securities as collateral. The net value of the account — the securities’ market price minus the loan — must stay above a minimum margin requirement set by the broker. That requirement serves as a safety buffer for the broker if prices fall.
When the value drops too low, the broker demands additional cash or securities to restore the collateral. This demand is a margin call.
If the investor cannot meet it, the broker sells the holdings to cover the loan. In the 1920s, those requirements were astonishingly loose. Leverage rates of up to 90 percent debt were not uncommon, leaving investors perilously exposed to even a modest decline.
According to a 1994 paper by Peter Rappoport and Eugene N. White in The American Economic Review, titled “Was the Crash of 1929 Expected,” margin requirements had actually begun rising to historic new levels in late 1928 or early 1929.
Peak rates on brokers’ loans reached 40 to 50 percent, and brokerage houses demanded higher margins. But for many investors already leveraged at 90 percent, even those higher requirements came too late to stop the unwinding. When the market contracted, those investors received margin calls they could not satisfy. Their shares were sold, driving prices lower and triggering new margin calls on other accounts.
Underlying Weaknesses of the Roaring Twenties
The previous decade, known as the Roaring Twenties, had brought rapid industrial expansion across the United States. Much of the profit from that growth flowed into speculative stock buying. Ordinary citizens, frustrated by low interest rates on bank deposits, put their modest savings into stocks.
By the late 1920s, however, the economy was showing real trouble. Farmers faced deep debt from overproduction and falling crop prices.
Manufacturers of consumer goods could not sell their output because wages were too low and purchasing power too weak. Factory owners cut production and laid off workers, reducing demand further. Yet investors kept buying shares in those very industries, driving stock prices far above any reasonable value.
In September 1929, experienced shareholders began to realize that prices could not keep climbing. They started selling their holdings.
Share values stalled and then fell, encouraging more selling. Panic set in. On a Thursday in late October, a record number of shares changed hands on the New York Stock Exchange.
The following Tuesday brought even more frantic trading. Leading bankers tried to halt the fall by buying stock at above-market prices, a tactic that had worked during a previous panic two decades earlier.
This time, it produced only a brief pause. The market kept dropping until the summer of 1932, by which time stocks had lost most of their pre-crash value.
Enduring Safeguards and Persistent Risks
Margin lending for stocks is nothing new; it became popular in the late 1800s to finance railroad construction. The mechanism itself remains alive today.
On modern U.S. futures exchanges, margins were formerly called performance bonds. Most exchanges now use the SPAN (Standard Portfolio Analysis of Risk) methodology, developed by the Chicago Mercantile Exchange in 1988, to calculate margins for options and futures. The same forced-liquidation dynamic can still cascade through markets today.
When prices drop sharply, margin calls can compel investors to sell assets, pushing prices down further and triggering additional calls. Congress responded to the 1929 crash by creating the Securities and Exchange Commission and passing laws that separate commercial and investment banking, prohibit market manipulation, and require companies to disclose financial information.
In the United States, the Federal Reserve under Regulation T now limits margin debt to 50 percent of the purchase price. Those safeguards have prevented a repeat of the 1929 disaster, but they do not eliminate the risk entirely. The crash of 1929 stands as the most devastating in American history, and its lesson about the dangers of borrowed money in a falling market continues to inform how regulators and investors think about financial stability.




