
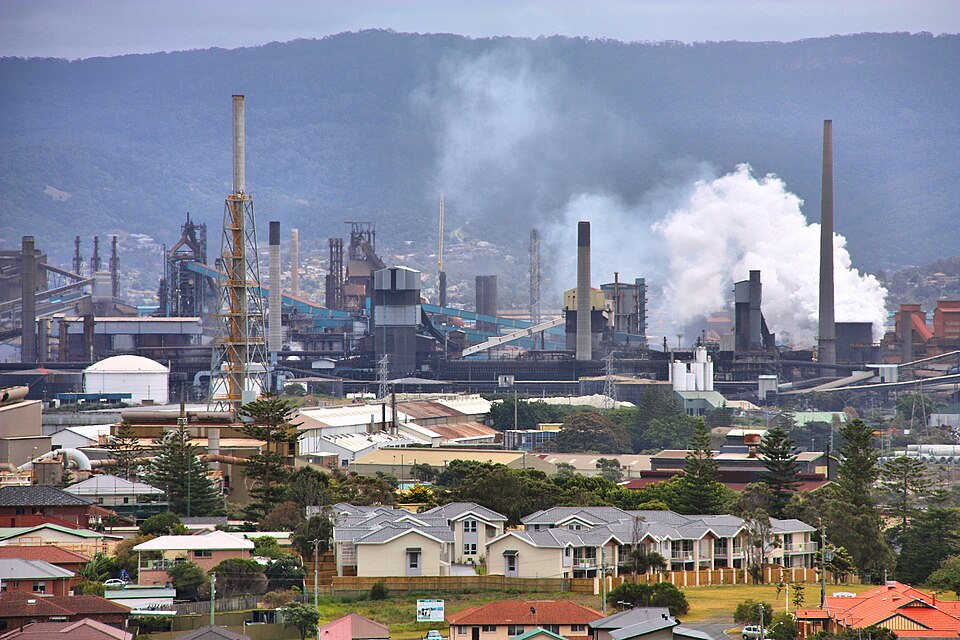
OTTAWA — The federal government is writing cheques for automation. A Quebec steelmaker got $52 million. That is a policy signal, not just a budget line.
What Ottawa is buying with that money is a bet that industrial automation matters as much as financial technology. The steel industry is not fintech.
But the logic is the same: machines doing work humans used to do, and doing it faster. The question nobody has answered yet is who answers when the machines get it wrong. That question is sitting on the desk of every Canadian financial regulator in 2026.
The industry analysis circulating this week does not pretend open banking is fully operational. It does not claim AI is client-ready.
What it does is lay out the gap between what the technology can produce and what a regulated institution is willing to act on. A companion Q&A in the same publication drew the line sharply: “Why ‘AI-generated’ is not the same as ‘client-ready’ in financial services.” That is the policy problem in plain language. A model can spit out a credit decision in milliseconds.
A bank cannot hand that decision to a customer and say “the model did it.” The regulator will not accept that answer. Not in Canada. Not in 2026.
The governance question is where the real action is. Another piece in the same coverage looked at Thomson Reuters and asked why governance lets that company move faster on AI.
The answer, implied clearly, is that the bottleneck is never the code. It is the organisational architecture. The rules.
The compliance framework. The human chain of accountability.
That is the piece Canadian policymakers are still assembling. The technology is here. The money is being spent.
But the regulatory architecture around autonomous systems is not keeping pace. A separate article in the same package carried a subheading that should worry every compliance officer in the country: “When systems fail, no one knows why.” That is not a hypothetical. It is a description of what happens when an AI-driven credit model starts rejecting applicants in a pattern no human can explain.
The regulator will want to know why. The applicant will want to know why.
The bank will have to produce an answer. If the system is truly autonomous, nobody will have one. Canada is spending heavily on automation across sectors.
The Quebec steelmaker investment is real money. It signals that the federal government sees industrial automation as a priority.
But spending money on the technology without spending equivalent effort on the rules that govern it is a policy gap with teeth. The industry analysis frames the conversation accurately: the technologies are reshaping the landscape. That is happening whether the rules are ready or not.
The question for Ottawa is whether the regulatory framework catches up before the first unexplainable failure lands on a minister’s desk. Nobody in the source material claims that open banking is fully operational in Canada. Nobody claims AI is client-ready.
What the coverage does is name the problem: the gap between what the technology can do and what the system is willing to act on. That gap is the policy space.
It is where the rules need to go. And it is where Canada is still writing the first draft.




