
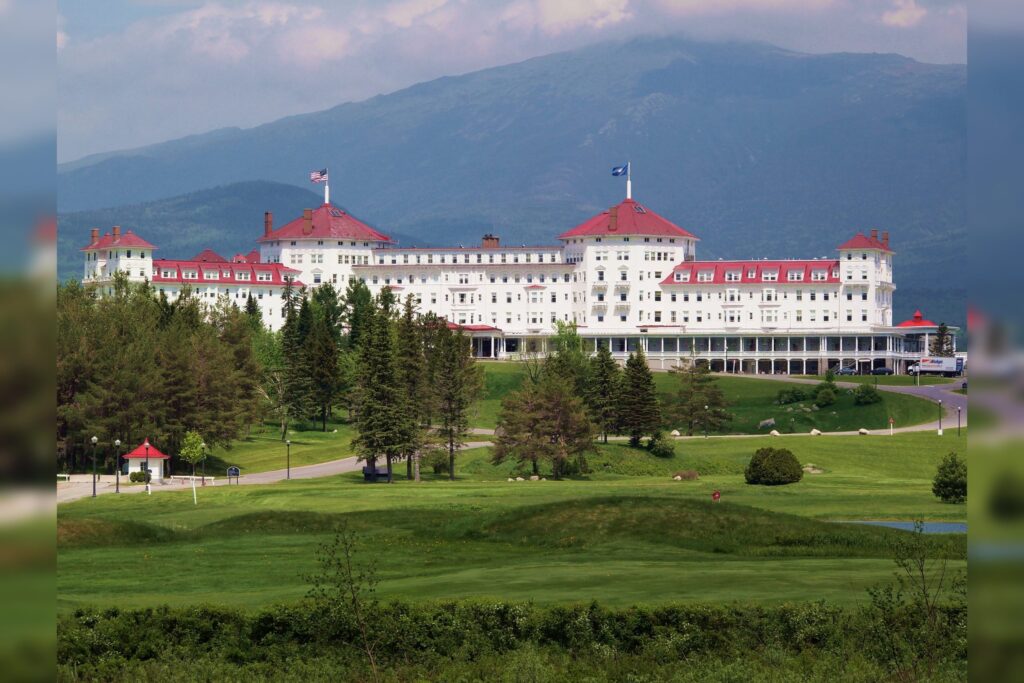
BRETTON WOODS, N.H., July 10 — The Bretton Woods Conference of July 1944, with 44 Allied nations gathered in this New Hampshire town, institutionalized the U.S. dollar as the world’s reserve currency. The agreement created a system of fixed exchange rates where currencies were pegged to the dollar, and the dollar itself was convertible to gold at $35 per ounce. The conference also established the International Monetary Fund and the World Bank.
The system was designed to prevent competitive devaluations and promote economic stability after the Great Depression and World War II. At the time, the United States held approximately 75 percent of the world’s official gold reserves.
The system worked until the 1960s. According to the record, U.S. inflation from the Vietnam War and social spending led to a growing trade deficit and gold outflows. The system effectively ended on August 15, 1971.
President Richard Nixon announced the suspension of dollar convertibility to gold, a move known as the “Nixon Shock.”
The Aftermath of the Nixon Shock
In December 1971, the Smithsonian Agreement attempted to salvage a modified version of fixed exchange rates. The accord devalued the dollar and widened exchange rate bands. It collapsed in 1973, ushering in the era of floating exchange rates.
Despite the end of gold convertibility, the dollar remained the dominant reserve currency. Sources familiar with the history note that this persistence was due to the lack of a viable alternative and the continued strength of the U.S. economy.
The Bretton Woods system represented a deliberate attempt to impose order on international finance after the Great Depression and World War II. Its architects sought stability through a rules-based framework anchored to the dollar and, ultimately, to gold.
Legacy and Current Relevance
The institutions created at Bretton Woods — the IMF and the World Bank — continue to operate today, though their roles have evolved significantly. The fixed exchange rate mechanism itself is long gone, replaced by a system where major currencies float against one another. The timeline shows a clear progression: the system worked until the 1960s, when U.S. fiscal pressures from the Vietnam War and social spending created a growing trade deficit and gold outflows.
Nixon’s August 1971 announcement was not a sudden decision but the culmination of mounting pressure. The Smithsonian Agreement that followed was essentially a stopgap measure, unable to hold the system together.
By 1973, the last remnants of Bretton Woods had dissolved. What remains is the dollar’s enduring role. The record shows that no other currency has emerged to challenge its reserve status, despite periodic speculation about the rise of alternatives.
The U.S. economy’s size, depth, and relative stability have sustained the dollar’s position. For analysts watching the international monetary system, the Bretton Woods story offers a cautionary tale about the limits of fixed exchange rate regimes.
The system’s collapse came when the anchor currency — the dollar — came under pressure from domestic inflation and external deficits. Those pressures, the record shows, ultimately proved incompatible with the fixed-rate architecture.
{“@context”: “https://schema.org”, “@type”: “NewsArticle”, “headline”: “From Bretton Woods to Nixon Shock: Dollar Hegemony Origins”, “description”: “BRETTON WOODS, N.H., July 10 — The Bretton Woods Conference of July 1944, with 44 Allied nations gathered in this New Hampshire town, institutionalized the…”, “datePublished”: “2026-07-10T09:30:00+00:00”, “author”: {“@type”: “Person”, “name”: “Ariel Antonio”}, “publisher”: {“@type”: “Organization”, “name”: “InfoPulse Today”, “url”: “https://newsfeed.infopulsetoday.com/”}}




