
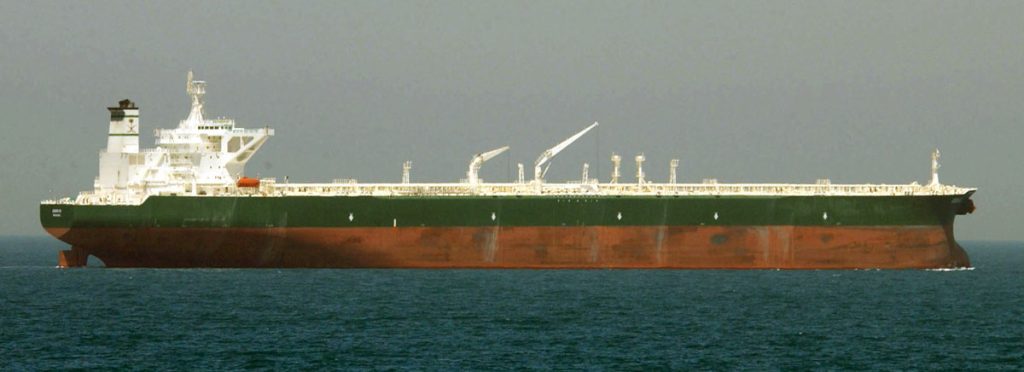
SINGAPORE, Sept. 1 — The oil shock triggered by the US–Iran conflict is still working its way through Asian currency markets, but the mechanics differ sharply from economy to economy, according to a new analysis from Economy in Brief. The letter, published Monday by Tian Yong Woon, notes that both sides exchanged strikes earlier this week — the first such exchange in about a month — and that shipping through the Strait of Hormuz remains severely disrupted.
That is effectively putting a floor beneath crude prices, sustaining inflation risks and worsening the terms of trade for oil-importing economies. The yen and the rupee have both been weak this year, but energy dependence is only part of the story.
On closer reading, unfavourable interest-rate differentials remain the principal constraint on the yen, while portfolio flows have amplified the rupee’s decline. The Indonesian rupiah’s pressure, by contrast, owes more to domestic politics and fiscal credibility than to the oil bill. Broad dollar strength is often blamed for the region’s currency weakness.
The catch is that the trade-weighted nominal dollar index has moved largely sideways.
India’s exposure
India’s vulnerability is particularly pronounced. Domestic crude production covers only a small share of consumption, leaving the economy highly exposed to global price movements. South Korea, Japan and Taiwan face similarly heavy import dependence, while China’s headline figures probably understate its underlying exposure because much of its refined production relies on imported crude.
For India, a deteriorating energy bill has coincided with financial-account pressure. Portfolio investors withdrew capital for an extended period after the conflict erupted in late February.
Those outflows reversed after the Reserve Bank of India introduced incentives in June to attract dollar deposits, allowing banks to offer attractive rates on FX deposits with the RBI subsidising hedging costs. The measures proved effective enough to be withdrawn ahead of schedule. Nevertheless, the rupee has recovered little of its earlier decline.
Indonesia’s different risk
Indonesia presents a different profile. Investor unease centres less on oil-import dependence than on the direction of fiscal policy and the broader political environment. Foreign ownership of rupiah-denominated government bonds has fallen below 13%, even as the outstanding stock of debt has continued to expand.
President Prabowo’s USD 230bn budget for 2027 targets a smaller deficit, but the letter questions whether that will be sufficient to restore investor confidence. The analysis references charts tracking Brent crude prices, Strait of Hormuz shipping volume, Asian nominal effective exchange rates, petroleum production versus consumption, India portfolio flows, Indonesian bond ownership and Indonesia’s budget deficit.
The question now is whether the relative calm in the Strait holds. If shipping disruption persists, the floor beneath crude prices stays — and the pressure on the rupee and yen, for very different reasons, is unlikely to lift.




