The story begins in a brokerage note dated August 26, 2026, where Motilal Oswal Financial Services lays out its case for Cummins India. The target: ₹6,400. The last traded price: ₹5,190. The implied upside: 23%. For those involved — the analysts, the fund managers, the retail investors watching from the sidelines — the numbers tell a story of conviction in an industrial stalwart.
What unfolded in the broader recommendation list places Cummins India alongside four other picks. JM Financial sees Apollo Hospitals Enterprise climbing to ₹10,446 from ₹8,700 — a 20% upside. The same firm puts Indian Hotels Company Ltd at ₹850, up 16% from ₹727. Emkay Global assigns an Add rating to TCS with a ₹2,600 target against ₹2,283. Anand Rathi backs Hindustan Aeronautics Ltd at ₹5,431, a 10% lift from ₹4,900. Brokerages remain positive on healthcare, hospitality, IT, industrial and defence stocks, spreading conviction across sectors.
At its heart, Cummins India’s story is one of engine manufacturing and allied activities stretching back to 1962. The company, headed by Jennifer Mary Bush, operates from Pune with a market capitalisation of 112266 crore as of the latest filings. Net profit for the year ended March 2025 stood at 2361.75 crore on revenue of 10,346.00 crore. The promoter group holds 51; foreign institutional investors 19.48; domestic institutions 20.82; the public 8.70.
For those involved in recent corporate actions, a postal ballot notice went out on November 6, 2026, seeking shareholder approval for a new managing director — Adebile Adedapo Adewunmi — and additional related party transactions with Cummins Inc. The board had met on November 4 for quarterly results. Earlier, on May 27, a final dividend of ₹46.00 per share was declared alongside the annual general meeting.
The financial profile shows a P/E ratio of 52.82, P/B of 14.72, ROE of 29.45, ROCE of 37.29. Debt-to-equity sits at 0.13 for the industry, with interest coverage at 158.85. Earnings per share (TTM): 83.85. Dividend yield: 1.43. Book value: 299.40.
Recent headlines add texture. Q2FY27 net profit fell 18.5% year-on-year to 507.17 crore despite 4% revenue growth. A 5.19 crore CGST penalty from Jaipur covering assessment years 2020-24 — the company says no material impact and is evaluating legal remedies. On the NSE, a block trade of 47,526 shares changed hands at ₹4,843.30 each, aggregating 23.02 crore. The shareholder register closed on October 15 for the director commission resolution.
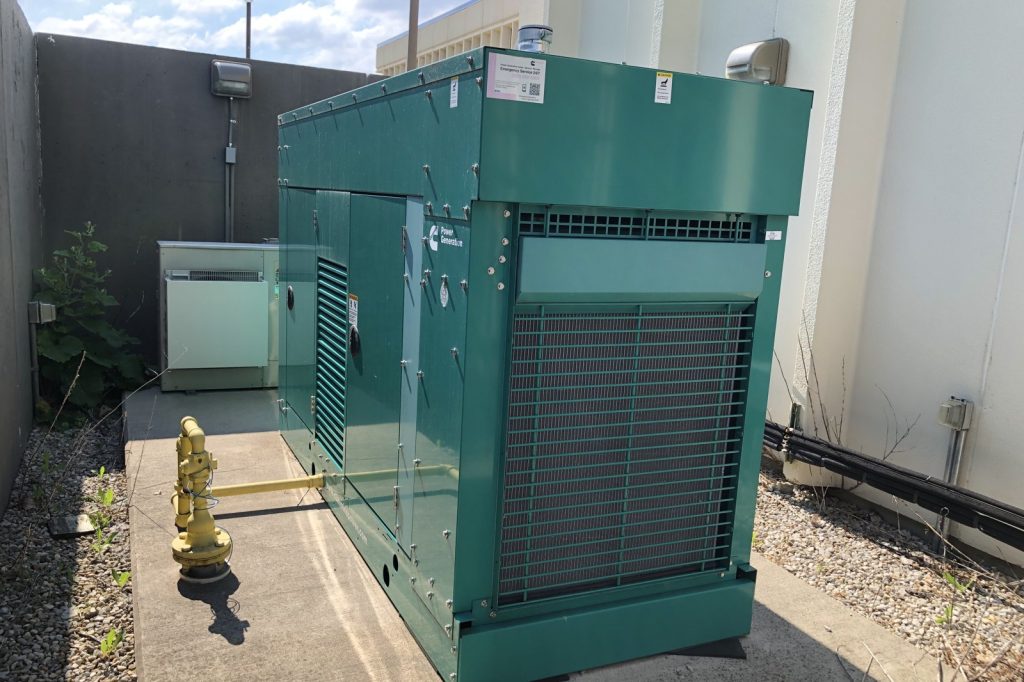
Through it all, Motilal Oswal’s Buy rating holds. The target price of 6400 represents not just a number but a view on where this engine maker — powering everything from heavy-duty trucks to power generation — might head next. The disclaimer accompanies every recommendation: views are the experts’ own, not the Economic Times’. But for investors tracing the arc from 1962 to 2026, the 23% upside is the latest chapter in a long industrial story.
Sources
- Stocks to buy in 2026 for long term: Cummins India, Indian Hotels among 5 stocks that could give 10-20% return – Brokerage Recommendations | The Economic Times
- Cummins India Ltd Share Price Today – Cummins India Ltd Stock Price Live NSE/BSE