
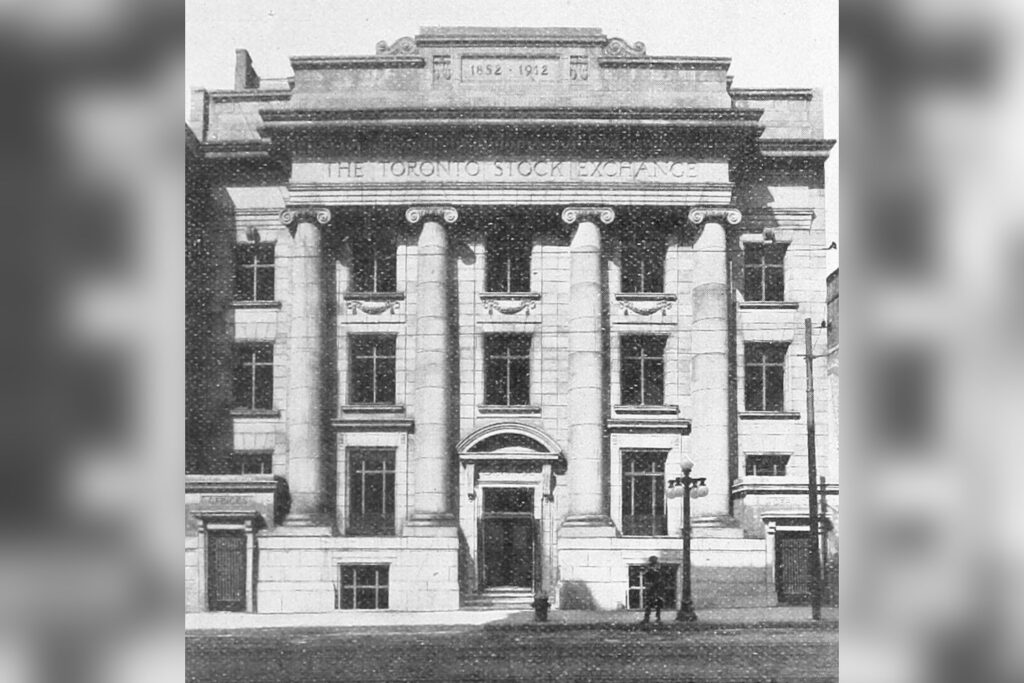
The Toronto Stock Exchange floor is a monument to Canadian caution. Suits, screens, the quiet hum of capital sliding from one blue-chip column to another. What you won’t find there is money for a rocket company.
Not the kind that explodes on a launchpad three times before it works. That kind of money goes south.
The complaint, now a familiar one in policy papers and conference calls, is blunt. Canada’s institutional investors prefer pipelines. Banks.
Real estate. Safe bets with predictable quarterly returns.
The kind of deep-tech, high-burn-rate startup that might one day challenge an aerospace monopoly? That is someone else’s problem. That is America’s problem.
The result is a pattern that has become a national habit. Canadian engineers dream up the idea. Canadian seed money gets it off the ground.
A Series A round buys some lab space and a few prototypes. Then comes the wall.
The jump to Series B — the capital needed to actually build hardware, launch a satellite, or certify an engine — is where the whole thing stalls. That is the funding gap. It hits hardest at the worst possible moment.
What happens next is predictable. The company gets acquired by an American firm.
The intellectual property moves south. The jobs follow. The headquarters relocates.
Canada is left with another story about the one that got away. A supply chain that feeds the United States. Canadian brains doing the early work.
American capital taking the payoff. The comparison to SpaceX stings because it lands close to home.
Elon Musk’s rocket company is now a monopoly on American launch capability. It got there by surviving a long, expensive, failure-prone slog. Canadian capital markets, as currently structured, are not designed to fund that slog.
They are designed to avoid it. There is no shortage of raw materials.
Canada has those. There is no shortage of engineering talent. Canada has that too.
The government talks about space and innovation. It talks about building a domestic tech ecosystem. But talk does not fund a Series B round.
Talk does not pay for a third engine test after the first two blew up. The forces behind this are structural.
Institutional investors in Canada manage money for pension funds and insurance companies. Their mandate is preservation of capital, not moonshots. A pipeline is a known quantity.
A rocket startup is a gamble. The system rewards the known quantity.
It punishes the gamble, even when the gamble could produce the next SpaceX. Where this leads is not hard to see. The pattern repeats.
Canadian early-stage work feeds an American supply chain. The IP moves. The jobs move.
The headquarters moves. And the Toronto Stock Exchange keeps humming along, moving capital from one safe column to another.
Nothing changes until the incentives change. Until the capital markets decide that funding a failure-prone rocket company is a risk worth taking. That day is not on the horizon.
{“@context”: “https://schema.org”, “@type”: “NewsArticle”, “headline”: “Toronto Stock Exchange’s cautious culture limits funding for high-risk ventures”, “description”: “The Toronto Stock Exchange floor is a monument to Canadian caution. Suits, screens, the quiet hum of capital sliding from one blue-chip column to another….”, “datePublished”: “2026-06-27T17:05:00+00:00T09:30:00+00:00”, “author”: {“@type”: “Person”, “name”: “Isabella Moore”}, “publisher”: {“@type”: “Organization”, “name”: “InfoPulse Today”, “url”: “https://newsfeed.2bme.xyz/”}}




