Oil prices remain firmly supported, with ICE Brent hovering around $110/bbl as markets stay focused on persistent risks to Middle Eastern supply. According to The Commodities Feed, this suggests the market is pricing in a significant risk premium, given the situation’s volatility.
Market Dynamics
Despite relatively strong Persian Gulf flows, oil prices remain well-supported amid ongoing tensions in the Middle East. The Commodities Feed notes that if flows continue uninhibited despite the geopolitical environment, the risk premium would likely erode slowly. However, there are no signs of this yet. Another major issue in the oil market is logistics, namely the record tanker freight rates due to the less efficient use of tankers resulting from developments in the Middle East.
Global Supply And Demand
China released output data showing that domestic crude oil production rose 0.6% month-on-month and 2.5% year-on-year to 4.45m b/d in September. Refineries processed a little over 14m b/d of crude over the month, up 0.4% MoM but still down 8.4% YoY. This is the largest amount of crude processed by Chinese refiners since March. According to The Commodities Feed, this suggests that China drew down crude oil inventories at a pace of a little more than 500k b/d, or 16m barrels through September. The numbers also suggest that apparent demand fell by 2.7% MoM and 15.2% YoY to 12.75m b/d in September.
Regulatory Developments
The US is considering steps to allow the sale of sanctioned tankers, which would increase tanker capacity in the legitimate market. The idea is to bring freight rates down and reduce the delivered cost of oil to destination. However, uncertainty remains about how much capacity this could add to the legitimate market. The process’s duration means it may not offer immediate relief. In other regulatory news, India’s suspension of sugar-based ethanol purchases by state-owned fuel retailers has eased concerns over tight global supplies. Sugar prices fell for a second consecutive session, touching US¢20.5/lb, following the announcement.
Broader Implications
The ongoing tensions in the Middle East and the resulting risk premium have significant implications for the global oil market. As The Commodities Feed notes, the market is pricing in a significant risk premium due to the volatility of the situation. This, combined with logistical challenges and record tanker freight rates, is likely to keep oil prices supported in the near term. Analysts note that the situation is being closely watched, and any developments in the Middle East could have a significant impact on the global oil market. According to officials, the goal is to bring stability to the market and reduce the risk premium, but this is likely to be a challenging task given the current geopolitical environment.
Chinese Industrial Production Trends
Data from China’s National Bureau of Statistics show that primary aluminium output rose 3.1% year‑on‑year to 3.9 million tonnes in September, with cumulative production for January‑September 2026 increasing 3.8% YoY to 35 million tonnes. This growth keeps annual aluminium output on track to near the government‑set capacity ceiling of roughly 45 million tonnes.
In the same month, crude steel production edged higher to 73.6 million tonnes. However, year‑to‑date steel output remains 2.9% below the previous year’s level, totaling 724.8 million tonnes for the first nine months of 2026. The modest rise in steel output comes amid continued weakness in China’s property sector, which has kept overall demand subdued.
Sources
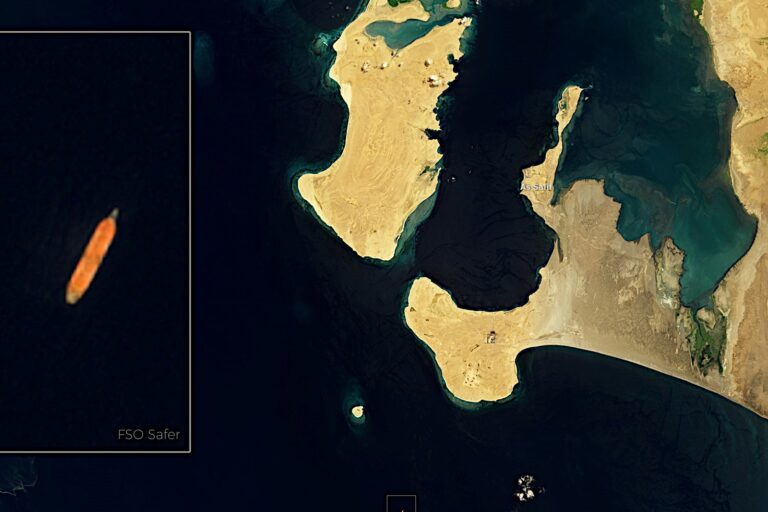
Photo: European Union , Copernicus Sentinel-2 imagery (Attribution)