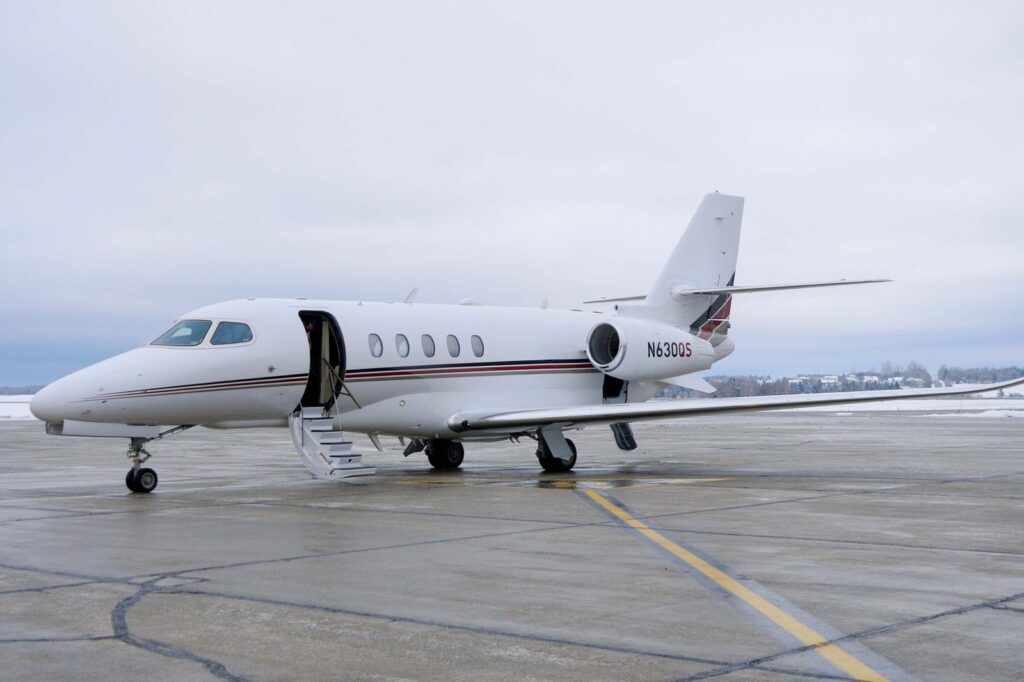
McKinsey’s 2026 report reveals that demand for private jets has hit record highs, with 3.9 million departures and 6.4 million flight hours in 2025, but a lack of pilots and maintenance capacity is creating a supply bottleneck. The bottom line: business aviation growth is now capped by pilot and aircraft shortages.
Business Aviation Growth
According to McKinsey, business aviation departures have increased by an average of 4.9% annually since 2019, reaching a record 3.9 million in 2025. Total flight hours increased from 4.7 million in 2019 to 6.4 million in 2025, a 37% gain. By the numbers, North America accounted for 70% of global flight hours in 2025, although Latin America and Asia-Pacific registered faster percentage growth. Investors will note that the global population of ultra-high-net-worth individuals increased by 5.6% annually between 2019 and 2025, driving demand for private aircraft.
Supply Chain Challenges
The figure that matters is not just the number of aircraft available, but also the supply chain of pilots, maintenance support, hangar space, and airport access. McKinsey says operators must ensure they have these resources to accommodate growing demand. The report draws on industry data and executive interviews, highlighting that delivering on the promise of private aviation is increasingly difficult due to pressure on infrastructure, airspace, and qualified personnel. Growing numbers of flights are putting pressure on infrastructure, airspace, and qualified personnel such as engineers and pilots.
Fractional Ownership And Demographic Drivers
Fractional ownership has emerged as the fastest-growing business aviation operating model, with fractional fleets increasing from 990 aircraft in 2019 to 1,510 in 2025, representing annual growth of 7.3%. NetJets and Flexjet accounted for 92% of fractional flight hours excluding turboprops. Demographic drivers, such as the transfer of wealth between generations, are also contributing to demand. NetJets Aviation President Patrick Gallagher notes that $80 trillion to $100 trillion in wealth will be transferred over the next 20 years, suggesting a potential source of demand for private aviation.
Operational Challenges
The surge in fractional ownership is exacerbating the pilot shortage, with operators struggling to find qualified personnel to support growing demand. Maintenance capacity, hangar space, and airport access are also becoming increasingly scarce, creating operational challenges for business aviation operators. According to McKinsey, the industry has entered a new phase in which securing aircraft is only part of the challenge. The report highlights that demand for private aircraft is outstripping supply, while growing numbers of flights and passengers are putting pressure on infrastructure, airspace, and qualified personnel. By the numbers, the shortage of pilots and aircraft is creating a bottleneck for corporate travel demand, capping business aviation growth.
Infrastructure and Cost Pressures
McKinsey identifies rising operating costs as a core challenge alongside aircraft availability, airport infrastructure, and maintenance capacity. The report states that delivering on the promise of private aviation is increasingly difficult because demand for private aircraft is outstripping supply, while growing numbers of flights and passengers are putting pressure on infrastructure, airspace, and qualified personnel such as engineers and pilots.
Operators must ensure they have pilots, maintenance support, hangar space, and airport access to accommodate growing demand. McKinsey says the industry has entered a new phase in which securing aircraft is only part of the challenge. The consulting firm’s inaugural State of Business Aviation in 2026 report also forecasts continued consolidation, growing demand for fractional ownership, and a shift toward leisure destinations.
Leisure Destinations And Wealth Projections
McKinsey’s inaugural State of Business Aviation in 2026 report forecasts a significant shift toward leisure destinations, identifying this trend as a primary driver of ongoing expansion. The consulting firm attributes the industry’s growth partly to increasing wealth, noting that the global population of ultra-high-net-worth individuals, defined as those with at least $30 million, increased by 5.6% annually between 2019 and 2025. This demographic shift is expected to sustain demand for private aircraft even as operational constraints persist.
Regional dynamics are also evolving, with McKinsey expecting North America’s share of the ultra-high-net-worth population to increase from 37% to 43% by 2031. While North America currently accounts for 70% of global flight hours, the report highlights that Latin America and Asia-Pacific have registered faster percentage growth in recent years. This geographic diversification suggests that demand for private aviation is broadening beyond traditional hubs, further complicating the supply chain for operators who must adapt to varied regional requirements.
The report also cites the coming transfer of wealth between generations as another potential source of demand. NetJets Aviation President Patrick Gallagher told McKinsey, “The transfer of wealth we have been hearing about for years suggests that around $80 trillion to $100 trillion will be transferred over the next 20 years.” This intergenerational shift implies a new cohort of potential users who may prioritize flexibility and leisure travel, reinforcing the trend toward non-business destinations and placing additional pressure on airport infrastructure and airspace capacity.
Historical Evolution Of Business Aircraft
The lineage of business aviation stretches back to the 1930s, when companies began purchasing single and twin-engined general aviation aircraft to meet specific business needs. Early adoption often involved surplus military transports or specialized variants, such as the Beagle B.206 purchased by Maidenhead Organ Studios in the United Kingdom in 1963 to facilitate the delivery of electronic organs. This era established the precedent for using aviation as a direct operational tool for corporate logistics rather than solely for executive transport.
The transition to jet propulsion marked a significant shift in capability and comfort. The first jet aircraft used for business purposes was the four-seat Morane-Saulnier MS.760 Paris, followed by the four-engined Lockheed JetStar in 1957, which was ordered by major corporations including Gulf Oil and Ford Motor Company. Subsequent decades introduced larger, bespoke models like the Gulfstream II in 1966, which offered greater range and cabin volume compared to earlier generations that prioritized speed and altitude.
Recent advancements have expanded the market into single-engine configurations. The Cirrus Vision SF50, first delivered in December 2016, stands as the first single-engine jet used for business purposes. In the turboprop sector, the Socata TBM, delivered in 1990, was the first single-engine business turboprop, later joined by the Pilatus PC-12 and Piper Meridian. These developments reflect a broader trend toward diversifying the fleet to accommodate various operational requirements and cost structures.
Sources
- Business aircraft
- McKinsey: Leisure flying is powering business aviation
- Four wildfire-fighting companies to watch in the blazing years ahead
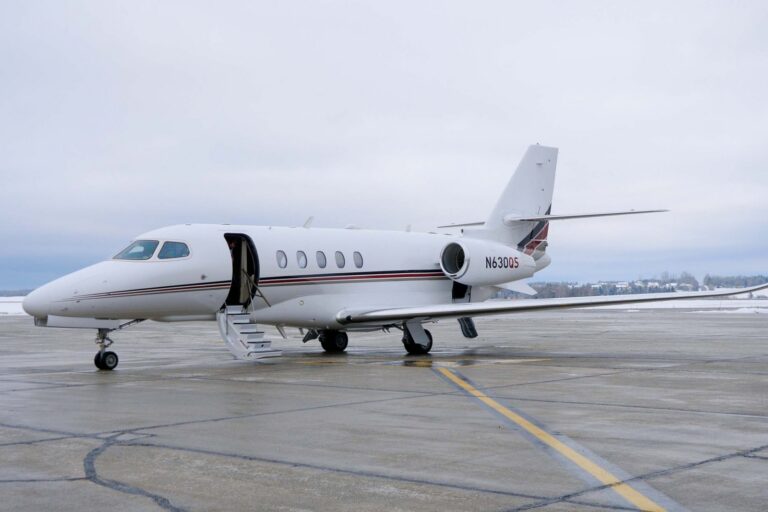
Photo: Quintin Soloviev (CC BY-SA 4.0)