
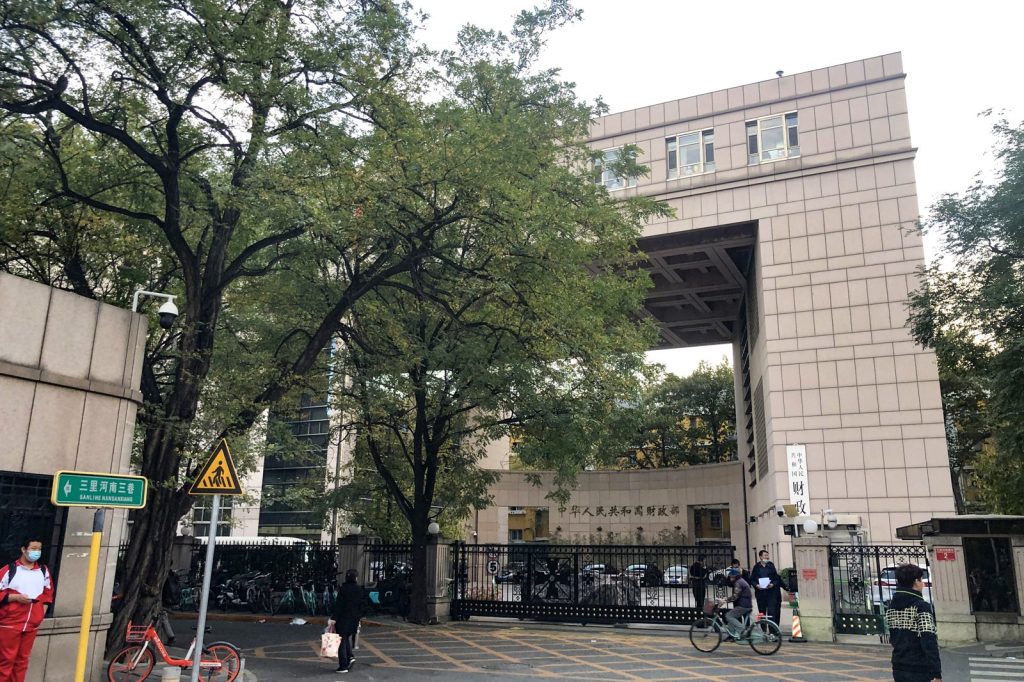
SHANGHAI, September 11 — China’s decision to scrap a thirteen percent export tax rebate on aluminium, announced by the Ministry of Finance in November 2024, is still reshaping the global market for the metal nearly two years on, with the policy’s architects arguing it was never the concession to foreign pressure that many outside observers assumed.
That reading comes from a paper published by the Center for China Analysis on May 8, 2026, titled “Strategic Shift in China’s Primary Aluminum Industry” and authored by Landon Thomas, an Affiliated Researcher at the center. Thomas argues the rebate cancellation is better understood as part of a strategic effort to rebalance an inefficient industry and realign incentives toward domestic priorities, rather than a preemptive move to defuse trade tensions.
A market that moved both ways
The immediate market reaction was sharp and split. London Metal Exchange prices spiked, while prices on the Shanghai Metals Market slumped as traders anticipated a significant drop in Chinese aluminium exports. For a country that produces nearly sixty percent of the world’s primary aluminium, the ripples were always going to be felt far beyond China’s borders.
Many outside observers read the policy as an attempt to head off escalating tariffs expected under a new Trump administration. The paper pushes back on that interpretation.
Officials noted the timing coincided with similar changes for copper and other goods, suggesting a broader industrial recalibration rather than a single-sector concession.
Where the metal is going instead
Aluminium is increasingly tied to electric vehicles and solar power, two sectors at the centre of China’s industrial planning. In the EV sector, a core pillar of Made in China 2025, the metal is widely used in vehicle structures and battery systems. Data shows battery electric vehicles contained roughly 85% more aluminium than internal combustion engine vehicles in 2022.
With EVs accounting for nearly half of all car sales in China in 2024, demand from the new energy vehicle sector is projected to rise from 2 million tons in 2023 to nearly 10 million tons by 2030. Solar energy represents another major source of demand.
In photovoltaic systems, aluminium is used extensively in panel frames, support structures and mounting systems. China added 277 gigawatts of solar capacity in 2024 alone, more than double that of the United States, and with each kilowatt requiring roughly 21 kilograms of aluminium, continued expansion implies substantial material demand. Together, these emerging sectors are increasingly serving as domestic outlets for aluminium production, offsetting the sector’s traditional reliance on construction and real estate.
Much of that output still finds its way to export markets, however, as EVs and solar products are exported overseas in large volume.
Early evidence, open questions
The paper’s executive summary states that the removal of the aluminium export tax rebate “reflects an effort to make production more efficient, curb excess capacity, and redirect production toward strategically important industries.” It adds that while it is too early to assess the policy’s long-term effectiveness, early evidence shows the sector is adjusting. Aluminium exports have declined modestly since the policy took effect. Whether increased domestic absorption will ultimately translate into greater productivity and efficiency gains across the sector remains unclear.
What to watch next is whether the projected demand from EVs and solar materialises at the pace the paper anticipates, and whether China’s aluminium producers can convert that domestic pull into the efficiency gains the policy was designed to force.




