
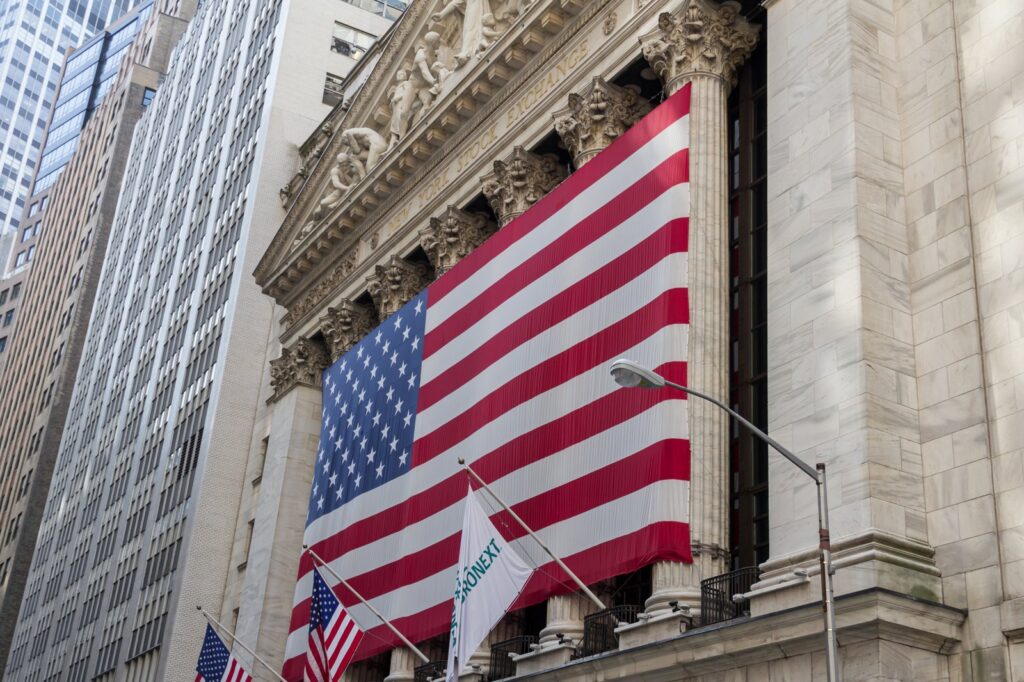
NEW YORK, October 16, 2026 — Wall Street is closely watching a surge in the Treasury term premium to 12-year highs as bond selloff pressures mount across markets.
What the Term Premium Is and Why It Matters
The term premium is the extra return investors demand for holding long-term Treasuries instead of rolling over short-term securities for the same period. It reflects compensation for risks like unexpected inflation, fiscal instability, or geopolitical shocks before the bond matures. Unlike inflation expectations or monetary policy outlook, the term premium is not directly observable and must be inferred from yield curves and models. Neel Kashkari, president of the Federal Reserve Bank of Minneapolis, has likened it to dark matter due to its indirect nature. Its rise signals growing investor unease about future uncertainties, even when inflation and rate expectations remain stable.
Recent Spike to 12-Year High and Bond Market Implications
US Treasury yields reached a 24-year high as a result. The 10-year term premium broke out to a 12-year high, according to market analysis. Frank Rybinski of Aegon Asset Management said multiple ways to calculate the term premium are all going higher, indicating the move has staying power. This surge has been a key factor in pushing Treasury yields upward, increasing borrowing costs across the economy and pressuring equity valuations.
Drivers: Fiscal Uncertainty, Geopolitical Risks, Broken Correlations
Investors are demanding greater compensation for holding duration amid mounting fiscal and geopolitical uncertainty. Macroeconomic uncertainty, breakdowns in usual stock-bond correlations, rising debt supply, and fiscal policy worries are contributing to the term premium rise. Barclays researchers led by Demi Hu said these factors are all playing a role in the repricing. The term premium reflects protection against unpredictable turns like geopolitical shocks and government fiscal crises before long-term bonds mature. No single catalyst has been identified, but the confluence of these pressures is reshaping investor behavior.
Impact on Borrowing Costs and Wall Street Sentiment
The rise in the term premium is fanning fears of a potential shift that will heap pressure on an already battered market and keep borrowing costs elevated across the economy. Wall Street is closely monitoring the term premium as a signal of market stress and shifting investor sentiment. Higher Treasury yields increase the cost of financing for businesses, mortgages, and government debt, which can weigh on corporate profits and consumer spending. As the premium climbs, equity markets face headwinds from higher discount rates and reduced risk appetite.
Federal Reserve Perspective and Policy Implications
While the term premium is distinct from the current outlook for inflation and the direction of monetary policy, its rise complicates the Federal Reserve’s assessment of financial conditions. Officials watch it closely as a barometer of investor confidence and risk appetite. A sustained increase may signal that markets are pricing in greater long-term risk, which could influence policy deliberations even if inflation data remains within target ranges. The Fed does not directly control the term premium, but its movements affect the transmission of monetary policy through long-term interest rates.
What Comes Next for Markets and Investors
As the term premium remains elevated, investors are reassessing portfolio allocations and duration exposure in response to persistent uncertainty. Market participants are increasingly scrutinizing fiscal trajectories and geopolitical flashpoints that could further influence long-term risk perceptions. The sustained rise in the term premium suggests a shift in how investors price uncertainty, even in the absence of clear inflation or policy triggers.
Analysts note that without a single identifiable catalyst, the term premium’s movement reflects a broader recalibration of risk across asset classes. This environment may lead to continued volatility in Treasury markets and heightened sensitivity to macroeconomic surprises. Investors are likely to demand greater transparency and resilience in fiscal and monetary frameworks as they navigate an era of elevated term premiums.
Historical Context of Wall Street’s Financial Influence
Wall Street’s evolution from a 17th-century Dutch settlement street to the epicenter of American finance provides context for its current role in monitoring market signals like the term premium. Originally known as Het Cingel (“the Belt”) in New Amsterdam, the street hosted a defensive wall built by enslaved Africans and white colonists under Peter Stuyvesant’s orders in 1653. After the English takeover in 1664, it became a hub for securities trading and later housed New York’s city hall, which evolved into Federal Hall. By the 19th century, financial institutions increasingly dominated the area, and the early 20th century saw the construction of landmark skyscrapers such as 40 Wall Street, once the world’s tallest building.
Today, the Wall Street area remains anchored by the New York Stock Exchange (NYSE), the world’s largest stock exchange by market capitalization, and the Federal Reserve Bank of New York. It also hosts major financial institutions including commercial banks, insurance firms, and brokerage offices that support exchange activities. The district’s global economic influence stems from its concentration of capital markets, trading infrastructure, and financial services, making it a natural focal point for assessing shifts in investor sentiment such as the recent rise in the Treasury term premium.
Origins of the Term Premium Concept in Financial Theory
The term premium concept traces back to mid-20th century financial economics, emerging from efforts to explain deviations in long-term bond yields beyond expectations of future short-term rates. Early formulations by economists such as Irving Fisher and later John Hicks laid groundwork for distinguishing between expected returns and risk compensation in fixed income markets. The modern understanding gained traction through the expectations hypothesis and its limitations, prompting researchers to develop models that isolate the unexplained portion of yield spreads as compensation for bearing interest rate and inflation uncertainty over time. This theoretical evolution established the term premium as a key metric for gauging market perceptions of long-term risk, independent of central bank policy forecasts or inflation outlooks.
Sources
Photo: Dietmar Rabich (CC BY-SA 4.0)




