
NEW YORK, July 20 — The dot-com bubble, which crested on March 10, 2000, stands as a cautionary tale of speculative excess — one that investors in today’s data-center boom might be wise to reacquaint themselves with. The Nasdaq Composite rose 600% from 1995 to its peak, only to shed 78% of its value by October 2002, wiping out the entire run-up. Venture capital, once poured indiscriminately into startups with little more than a “.com” suffix, evaporated.
The history is dense with names that became shorthand for hubris: Pets.com, Webvan, Boo.com, WorldCom, NorthPoint Communications, Global Crossing. WorldCom survived briefly as MCI before being acquired by Verizon in 2006.
Others — Lastminute.com, MP3.com, PeopleSound — were snapped up, but at fractions of their former valuations.
The Boom and Bust
The mania did not emerge from nowhere. The 1993 Mosaic browser opened the commercial internet’s door. Home computer ownership in America climbed from 15% to 35% between 1990 and 1997.
Lower interest rates, the 1997 Taxpayer Relief Act’s cut to capital gains taxes, and then-Federal Reserve Chair Alan Greenspan’s supportive remarks on stock valuations all fed the fire. The 1996 Telecommunications Act further deregulated the sector.
By the time the bubble burst, the Nasdaq’s price-earnings ratio sat at 200 — more than double Japan’s Nikkei 225 peak of 80 at the height of its own asset-price bubble in 1991. Some stocks reached stratospheric heights. Qualcomm shares rose 2,619% in 1999 alone.
Twelve other large-cap stocks gained more than 1,000% that year; seven more climbed over 900%. Large, established firms were not immune to the frenzy or the crash.
Amazon lost enormous market value, and Cisco Systems shed 80% of its stock price. The collapse revealed that valuations had been untethered from earnings, and the correction was brutal.
Causes and Comparisons
Historians have long catalogued such booms. The dot-com era is compared to the railroad boom of the 1840s, the automobile frenzy of the 1900s, the radio bubble of the 1920s, the television craze of the 1940s, the transistor-electronics surge of the 1950s, the time-sharing computer boom of the 1960s, and the home-computer and biotechnology bubbles of the 1980s. Each shared a common pattern: a transformative technology, an influx of speculative capital, and a painful reckoning when expectations outpaced reality.
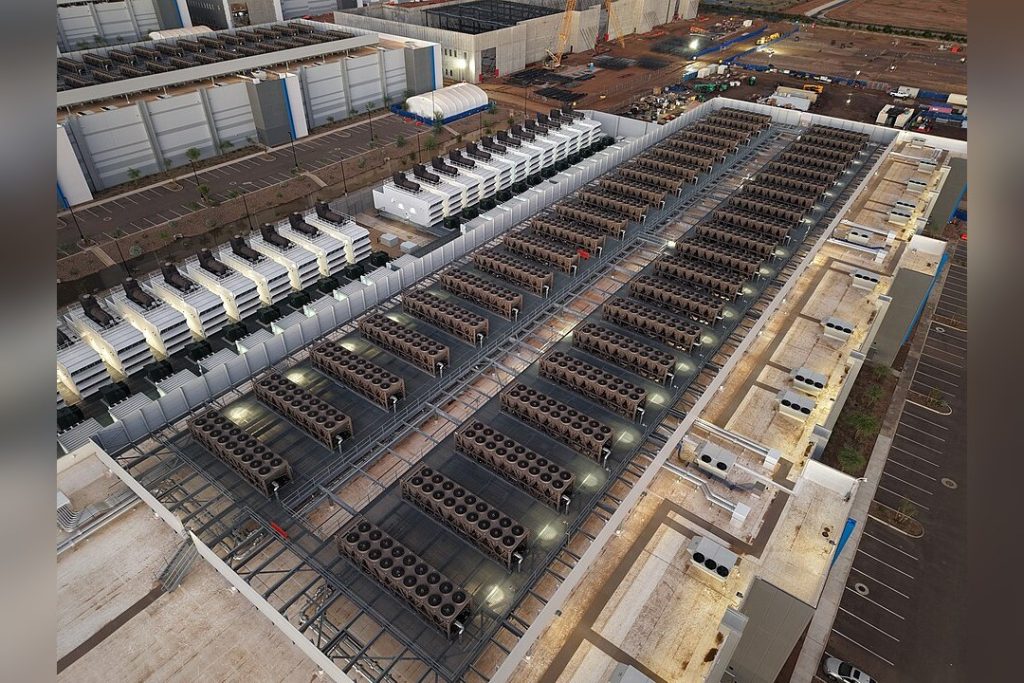
Today’s data-centre buildout draws direct comparisons to the dot-com era for its rapid investment and speculative risk. The parallels are noted by analysts who point to the same ingredients: a revolutionary technology wave — artificial intelligence and cloud computing, in this case — combined with low interest rates and a willingness to fund infrastructure at scale.
For all the noise, the salient point may be that history, while never repeating exactly, has a habit of rhyming. Notably, the 1990s boom was fuelled by a belief that the internet would transform everything. It did, but the transformation took longer and cost more than the early financiers had imagined.
Many of the companies that survived — Amazon and Cisco among them — eventually justified their valuations, but only after long years of losses and doubt. The data-centre builders of 2026 will hope that they, too, eventually see the returns their investors are betting on.
What to watch next is whether the current wave of capital into data-centre infrastructure produces a similar pattern of winners, failures, and consolidations. The dot-com bubble’s legacy is not simply a cautionary tale; it is also a reminder that transformative technologies do create lasting value — but not always for the investors who pile in first.




