
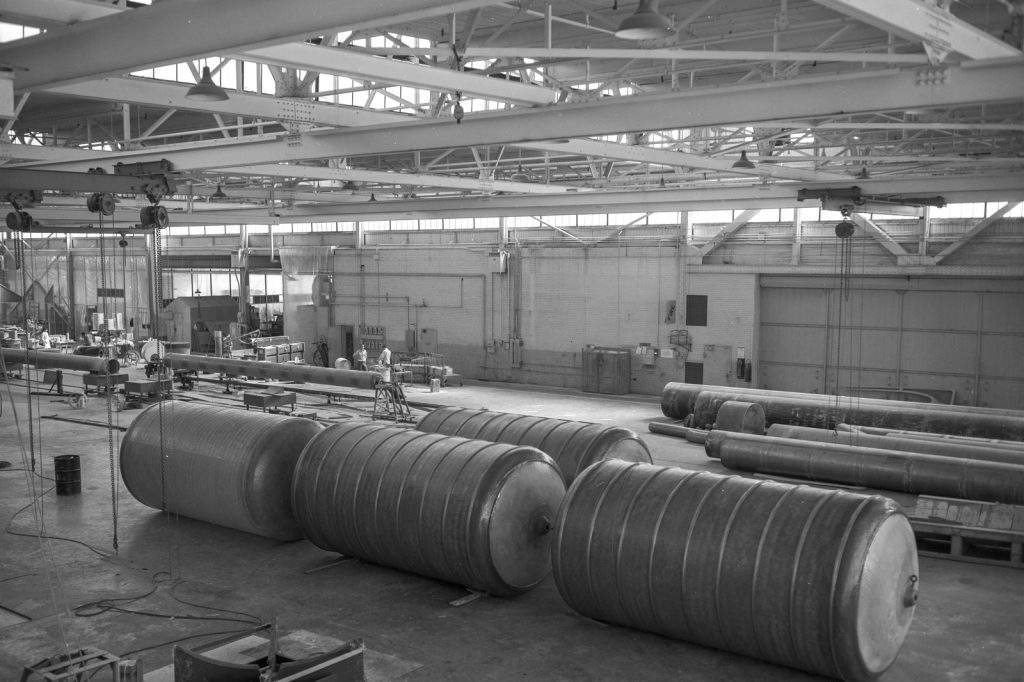
CHICAGO, July 25 — Manufacturing cost is more than a line item on a balance sheet. It is the sum of every resource consumed in making a product — every raw material, every hour of labour, every kilowatt of electricity that keeps the factory floor lit. For families whose livelihoods depend on a plant, this cost breakdown carries weight far beyond the accounting department.
The textbook “Fundamentals of Cost Accounting” by Lanen, Anderson, and Maher (McGraw Hill, 2008) defines three distinct categories that together form manufacturing cost: direct materials, direct labour, and manufacturing overhead. Understanding those categories, the authors explain, is essential for analysing production efficiency and profitability in any manufacturing business.
Direct materials: the substance of products
Direct materials are raw materials that physically become part of the finished product. Operations such as welding, cutting, and painting add value to these materials as they move down the line. For the workers who handle them, these are not abstract inputs; they are steel sheets, plastic pellets, or fabric rolls that become parts of automobiles, appliances, or furniture.
The cost of direct materials shapes decisions about sourcing and inventory. If steel prices rise, the effect ripples through the plant — and potentially into the paycheques of the people who depend on consistent production runs.
Direct labour: the hands that build
Direct labor cost covers those workers who are easily identified with the production of a specific product. Assembly line workers are the classic example. For the families of these workers, direct labour cost represents the paycheck that comes home each week — the money that pays rent, buys groceries, and covers the mortgage.
When managers scrutinise manufacturing costs, direct labour is often the most visible human factor. It is a cost tied to a person, not a machine or a material.
That human side makes wage negotiations, productivity incentives, and shift scheduling matters of real consequence on the factory floor.
Manufacturing overhead: the unseen engine
Manufacturing overhead includes all other manufacturing expenses not classified as direct materials or direct labour. This category covers a wide range of costs: indirect labour such as supervisors and the material handling team; indirect materials such as lubricants, grease, and water; and other indirect costs like machine depreciation, land rent, property insurance, electricity, freight, and transportation.
For the workers in a plant, overhead costs may feel invisible — the supervisor who keeps the line moving, the electricity that powers the welding equipment, the rent on the building that shelters their work. Yet these costs are just as essential as the raw materials and the labour itself.
Without properly lubricated machinery, production stops. Without property insurance, a fire could shut the doors permanently. Manufacturing overhead can be harder to track than direct materials or direct labour, but it is no less real.
A company that underestimates these indirect costs may find its total delivery cost higher than expected, squeezing margins and threatening the jobs that depend on a profitable operation.
Why it matters for people and profitability
The three categories — direct materials, direct labour, and manufacturing overhead — together form the manufacturing cost, which is a factor in the total delivery cost of a product. For the families of factory workers, this means that every decision about sourcing, staffing, and facility maintenance ultimately affects job stability. A plant that controls its manufacturing costs effectively is more likely to keep its doors open and its people employed.
The classification system explained by Lanen, Anderson, and Maher is standard in cost accounting. It gives plant managers, financial analysts, and executives a common language for discussing where money goes during production.
But behind every dollar of direct labour is a worker on the line. Behind every dollar of overhead is a supervisor ensuring safety and quality. And behind every dollar of direct materials is a supply chain that connects the factory to the global economy.
As manufacturers continue to face pressures from global competition and shifting demand, the human side of these cost categories will remain central. For the families that depend on factory work, understanding how manufacturing cost is built — and what it means for the company’s efficiency — is not an abstract exercise.
It is a matter of economic security.




