
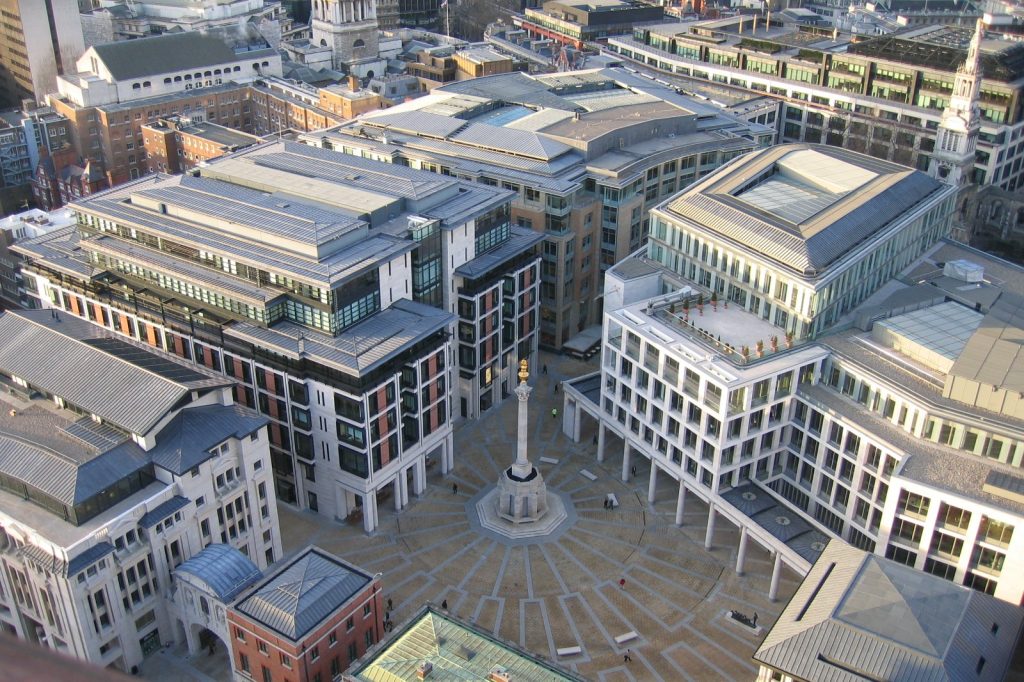
LONDON, September 5 — The London Stock Exchange has shed roughly 40% of its listed companies over the past decade, even as the City of London’s broader financial sector continues to expand. The mechanics here are simple: takeovers, delistings and a dearth of IPOs have stripped the market. In 2015 the exchange hosted about 1,300 issuers; by early 2025 that tally had slipped to fewer than 800, a contraction of approximately 40% according to the New Financial report released the week of March 10, 2025.
The catch is that fast‑growing firms are opting to list in New York or other global hubs, drawn by deeper pools of capital and more flexible regulatory regimes. William Wright, managing director of New Financial, attributes the slump to a wave of takeovers and the scarcity of fresh IPOs.
On closer reading, the shift signals a structural preference for offshore equity over a domestic public market.
City’s Economic Engine
Meanwhile, the City of London is thriving. The City of London Corporation’s 2024 economic impact study notes that financial and related professional services pump over £100 billion (approximately US$127 billion) into the UK economy each year and sustain employment for over 2.3 million people nationwide. The claim is that a robust public market underpins this output, but the data shows the sector’s growth is being driven largely by private‑market activity, fintech and foreign‑exchange trading, which are less dependent on listed equities.
In December 2022 Chancellor Jeremy Hunt announced the ‘Edinburgh Reforms’ to make the UK listing regime more attractive, easing rules on dual‑class share structures and trimming the free‑float requirement. The claim is that these changes would reverse the listing decline, but the trend has persisted.
High‑profile relocations, such as building‑materials giant CRH in 2023 and gambling group Flutter Entertainment in 2024, illustrate that the reforms have not succeeded in retaining marquee listings.
Broader Implications
Despite the contraction, the LSE remains a global heavyweight, with a total market capitalization exceeding £3 trillion (approximately US$3.8 trillion) as of early 2025. The catch is that its relative position has slipped compared with US exchanges, a point underscored by Wright’s observation that the UK’s equity capital markets are ‘hollowing out’ while banking, insurance and asset management stay robust. For retail investors, the shrinking public arena narrows direct access to corporate growth, raising long‑term competitiveness concerns.
On closer reading, the next chapter will hinge on whether further regulatory tweaks can stem the outflow of listings or if the City will double‑down on its non‑listed strengths. Watch for new policy signals and any shift in corporate listing strategies as the market recalibrates.




