
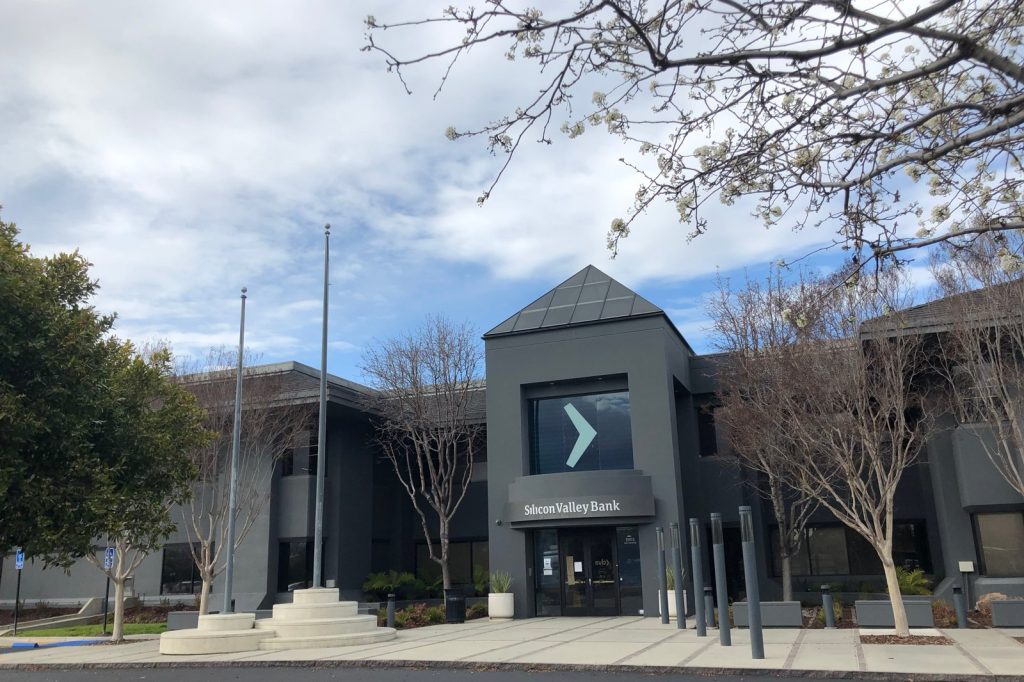
On March 10, 2023, Silicon Valley Bank (SVB) ceased operations after a rapid bank run, becoming the third‑largest bank failure in U.S. history and the biggest since the 2008 financial crisis. The SVB shutdown occurred alongside the March failures of Silvergate Bank and Signature Bank, underscoring a broader wave of instability in the sector.
SVB’s troubles stemmed from a strategy adopted after 2021 to boost returns on its expanding deposit base. The bank markedly increased its holdings of long‑term securities, classifying them as “hold‑to‑maturity” assets with the intention of keeping them until they matured. However, the Federal Reserve’s aggressive interest‑rate hikes aimed at curbing inflation caused the market value of those bonds to fall sharply throughout 2022 and into early 2023, creating sizable unrealized losses.
The dip in bond values was only one side of the pressure. Higher rates also raised borrowing costs across the economy, prompting many of SVB’s clients—particularly venture‑backed firms—to draw down deposits to meet liquidity needs.
Faced with a mounting outflow, the bank announced on March 8, 2023 that it had sold more than $21 billion of securities, secured $15 billion in borrowing, and planned an emergency sale of treasury stock expected to generate $2.25 billion. The disclosures, coupled with warnings from prominent Silicon Valley investors, intensified depositor anxiety. These emergency measures proved insufficient.
The sale of a large portion of the securities portfolio and the heavy borrowing signaled the bank’s precarious liquidity position, while the planned stock sale was a last‑ditch effort to raise capital. Despite the actions taken, withdrawals continued unabated, and the institution could not restore confidence.
When the failure was officially announced on March 10, the collapse sent a clear signal about the risks of rapid growth without robust risk management, especially in an environment of rising interest rates. It highlighted how a shift in monetary policy can simultaneously erode the value of long‑dated assets and increase demand for cash from borrowers. The ramifications extend beyond SVB’s immediate clientele. Regulators, lawmakers, and market participants are now scrutinizing the episode for lessons on oversight and capital adequacy.
The episode has already sparked debate over whether tighter regulations are needed to prevent similar breakdowns, particularly as the Federal Reserve continues to raise rates to combat inflation. Looking forward, the health of other banks with comparable asset‑liability structures will be closely watched.
The SVB failure serves as a reminder that banks heavily invested in long‑duration securities may face heightened vulnerability when rates climb. Ongoing monitoring of liquidity positions and stress‑testing practices is expected to become a priority for supervisors. In the weeks ahead, attention will focus on how policymakers respond, the impact on SVB’s former customers, and any broader spillover effects on the financial system.
The episode underscores the need for vigilance as the banking sector navigates a higher‑rate landscape, with the goal of averting future collapses of comparable magnitude.




