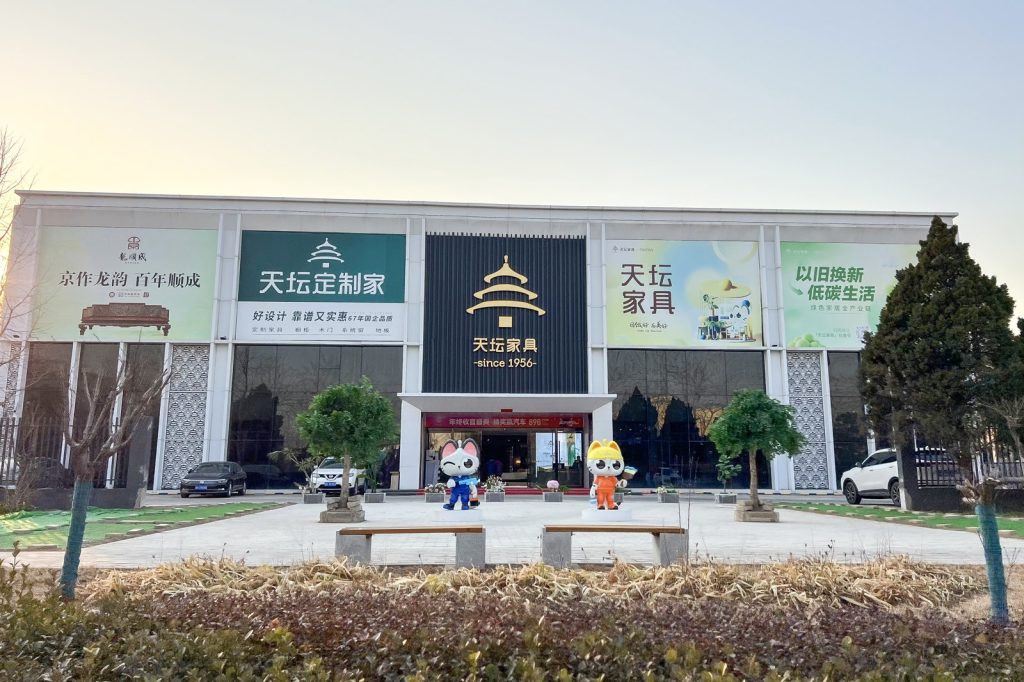
Beijing, September 9 — The story begins with Chinese home‑furnishing enterprises turning their gaze away from the crowded skylines of first‑tier cities and toward the quieter streets of county‑level markets. What unfolded in the middle of 2025 was a strategic pivot driven by slowing growth, fierce competition and soaring traffic costs in the metropolises that had long been the industry’s playground.
At its heart lies a striking shift in affordability: the price‑to‑income ratio for housing in third‑ and fourth‑tier cities fell from 9.5 in 2020 to 7.4 in the first half of 2025, lowering the threshold for home purchase and unlocking fresh demand for renovation and furnishing.
County‑Level Markets Gain Momentum
For those involved, the numbers tell a compelling story. Over 1,800 counties host a permanent resident population of about 450 million in urban districts and towns—nearly one‑third of China’s urban populace. Their aggregate economic output swelled from 30 trillion yuan (about US$4.2 trillion) in 2020 to 54 trillion yuan (about US$7.6 trillion) in 2024, now accounting for roughly 40% of the nation’s GDP.
Consumption resilience in these areas outpaces that of first‑tier cities, with expenditure growth significantly outpacing first‑tier cities.
Consumer Trends Shaping the New Landscape
The 2025 Black Ant Capital Consumer Trend Research Report highlights four county‑level consumption trends that are reshaping buying behaviour. First, shoppers are moving from “external prestige” to “internal substance,” favouring quality and comfort over status symbols. Second, “shared companionship” has risen in importance, with families seeking products that support collective living.
Third, “folded consumption” blends extreme cost‑effectiveness with premium upgrades—think a modest 9.9‑yuan eyeshadow purchased alongside a 15,000‑yuan gold bracelet. Finally, resilience amid financial pressure persists, underpinned by high home‑ownership rates and low loan ratios.
Opportunities for Home‑Furnishing Firms
Guided by the “New Home Furnishing Paradigm,” firms are now exploring four concrete opportunities. Retail spaces are being upgraded into experience hubs that combine design consultation, lifestyle displays and light social functions. Companies are adapting to content‑driven, near‑field, cost‑effective channels that reach shoppers where they live.
Additional tiered strategies address the spectrum of demands—from housing renewal and partial renovation to whole‑house customization and soft‑furnishing upgrades. McKinsey predicts that by 2030, sinking markets will contribute over 66% of China’s total incremental personal consumption, underscoring why exploring county‑level markets has shifted from optional to mandatory strategic priority.
Looking ahead, observers will watch how quickly major furnishing chains roll out experience‑focused stores across the counties, how the blended “folded consumption” pattern evolves, and whether the resilience of county‑level demand can sustain the sector’s growth as urban saturation deepens. The next chapter will reveal whether the new focus on China’s heartland can rewrite the playbook for home‑improvement businesses worldwide.